If you've got some money to invest and you're trying to decide between an ISA and a pension, you're asking the right question. Both offer significant tax advantages. Both can grow your wealth over time. But they have fundamentally different rules about when you can access your money, how they're taxed, and who they're best suited for.
Here's a practical breakdown to help you decide.
The basics
What is a pension?
A pension is a long-term savings pot designed for retirement. You can't normally access it until age 55 (rising to 57 from 2028). The main types are:
- Workplace pension: Your employer contributes alongside you. Most UK employees are auto-enrolled.
- Personal pension (SIPP): A self-invested pension you manage yourself, choosing your own investments.
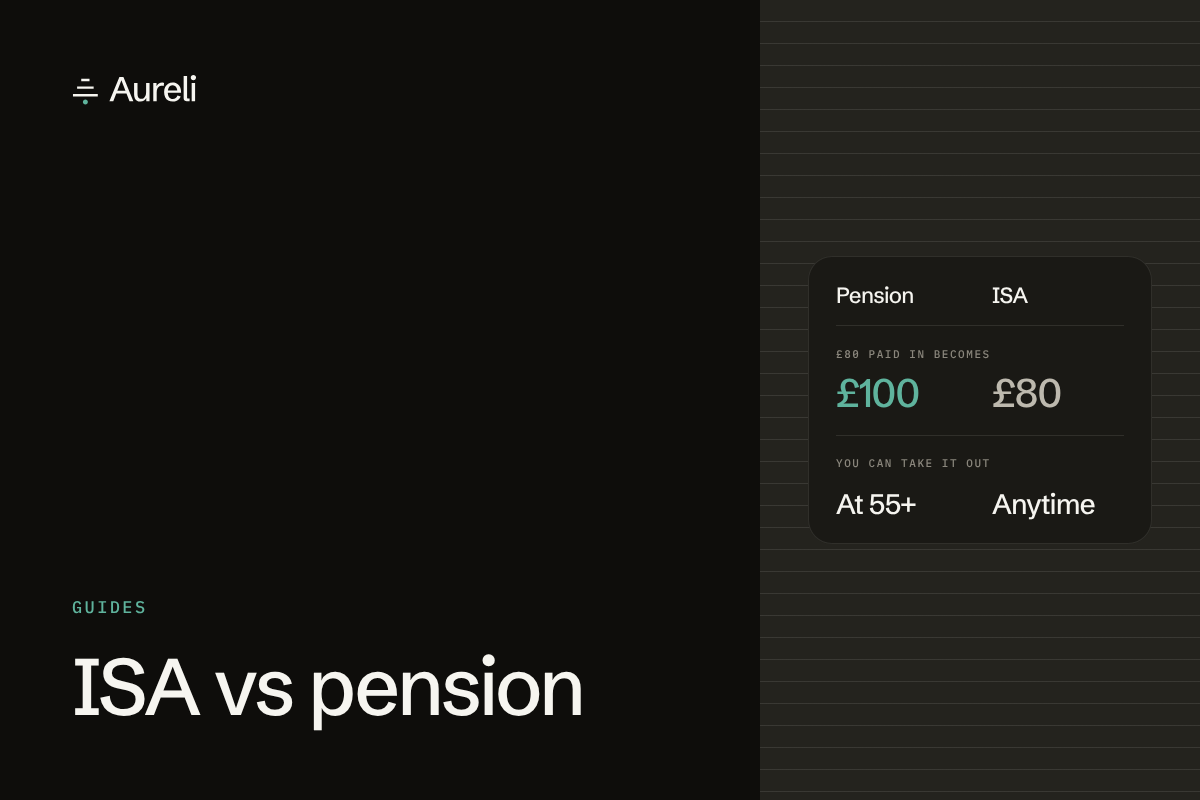
Tax treatment: Contributions get tax relief. A basic rate taxpayer contributes £80 and the government adds £20, making it £100 in your pension. Higher rate taxpayers can claim back a further £20 through their tax return, meaning £100 in the pension effectively costs £60. When you withdraw in retirement, 25% is tax-free and the rest is taxed as income.
What is an ISA?
An ISA (Individual Savings Account) is a tax-free wrapper for savings or investments. You can withdraw your money at any time. The main types for investing are:
- Stocks and Shares ISA: Invest in funds, shares, bonds, etc.
- Cash ISA: A savings account with tax-free interest.
- Lifetime ISA (LISA): A hybrid — 25% government bonus on contributions up to £4,000/year, but locked until age 60 or first home purchase (with penalties for other withdrawals).
Tax treatment: You contribute from money you've already paid tax on (no upfront relief), but all growth and withdrawals are completely tax-free. No tax on dividends, capital gains, or interest within an ISA.
The key differences
| Pension | ISA | |
|---|---|---|
| Access | Age 55+ (57 from 2028) | Anytime |
| Annual limit | £60,000 (2026/27) | £20,000 (2026/27) |
| Tax relief on contributions | Yes (20-45% depending on your rate) | No |
| Employer contributions | Yes (workplace pensions) | No |
| Tax on withdrawals | 75% taxed as income | Completely tax-free |
| Inheritance | Can be passed on (taxed after 75) | Can be passed on tax-free |
| Counts for benefits means testing | Generally no (until drawdown) | Yes |
When to prioritise your pension
You're getting employer matching
This is the closest thing to free money you'll find. If your employer matches your pension contributions — say, you put in 5% and they put in 5% — that's an immediate 100% return before any investment growth. Always contribute at least enough to get the full employer match. Not doing so is leaving part of your salary on the table.
You're a higher or additional rate taxpayer
The tax relief on pension contributions is more valuable the higher your tax rate. A 40% taxpayer effectively pays £60 for every £100 that goes into their pension. For a 45% taxpayer, it's £55. This is a significant advantage that ISAs simply can't match.
You won't need the money before retirement
If you're saving specifically for retirement and you're confident you won't need to access this money for decades, the pension's tax relief and employer contributions usually make it the better choice. The lock-up period is a feature, not a bug — it forces long-term thinking.
You want to reduce your taxable income
Pension contributions reduce your taxable income, which can be valuable if you're near a tax threshold. For example, if you earn £52,000, contributing £2,000 to your pension could keep you below the higher rate threshold, saving tax on that portion of your income.
The £100k tax trap: the strongest case for "pension first"
If your income sits between £100,000 and £125,140, the case above for prioritising your pension gets dramatically stronger. Above £100,000 of adjusted net income, your £12,570 Personal Allowance is withdrawn at £1 for every £2 you earn, on top of the 40% higher-rate tax you're already paying on that slice. The result is a marginal rate of roughly 60% on income tax alone, or around 62% once employee National Insurance is added — higher than the 45% additional rate that applies once you're clear of the band above £125,140.
A pension contribution large enough to bring your adjusted net income back under £100,000 restores the allowance and avoids that 60%+ rate entirely. Salary sacrifice makes it stronger still, since neither you nor your employer pays National Insurance on the sacrificed amount, and some employers pass their share of that saving into your pension too. The pension tax relief calculator shows what a contribution costs after relief at source, net pay or salary sacrifice, including that 60% band.
Inside this band, "pension first" isn't just the better option from the section above — it's usually the only one worth considering until you're back under £100,000. Only once you are should an ISA start competing seriously for the next pound.
When to prioritise your ISA
You might need the money before 55
The biggest advantage of an ISA is flexibility. If you're saving for a house deposit, building an emergency fund, or might need access to your investments in the next 5-20 years, an ISA is the obvious choice. There are no penalties for withdrawing.
You're already maximising employer pension contributions
Once you're getting the full employer match, additional pension contributions still get tax relief but don't get the employer boost. At this point, the ISA becomes more competitive, especially if you value flexibility.
You expect to be a higher rate taxpayer in retirement
Pension withdrawals are taxed as income. If you're a basic rate taxpayer now but expect to have a high income in retirement (perhaps from multiple pensions, rental income, or other sources), you might end up paying more tax on withdrawals than you saved going in. ISA withdrawals, by contrast, are always tax-free regardless of your income level.
You want to leave money to your family
ISAs can be inherited tax-free via the Additional Permitted Subscription (APS) rules, passing to your spouse or civil partner. Pensions can also be inherited, but if you die after age 75, your beneficiaries pay income tax on withdrawals.
You're approaching the Lifetime Allowance replacement rules
While the Lifetime Allowance was abolished in April 2024, the new "lump sum and death benefit allowance" of £1,073,100 still limits the tax-free amount you can take from pensions. If your pension is already large, further contributions may offer diminishing returns compared to ISA savings where everything is always tax-free.
The practical answer for most people
For the majority of UK workers, the optimal order is:
- Pension up to employer match — Free money. Always do this first.
- Emergency fund in a Cash ISA or easy-access savings — 3-6 months of expenses.
- ISA for medium-term goals — House deposit, career break fund, or investments you want flexible access to.
- Additional pension contributions — If you're a higher rate taxpayer and don't need access before retirement.
- Stocks and Shares ISA for long-term investing — Tax-free growth with no access restrictions.
The exact split depends on your tax rate, your age, your goals, and how much flexibility you need. But the "pension first for the match, then ISA for flexibility, then more pension if you're higher rate" framework works well for most people.
What about a Lifetime ISA?
The Lifetime ISA (LISA) sits in an interesting middle ground. You get a 25% government bonus (equivalent to basic rate tax relief), but the money is locked until age 60 or your first home purchase. If you withdraw for any other reason, you face a 25% penalty — which actually means you lose more than the bonus.
A LISA can make sense if:
- You're saving for your first home and will use it within the price cap (£450,000)
- You're a basic rate taxpayer without a generous employer pension scheme
- You're self-employed and want a retirement savings option with a government top-up
For higher rate taxpayers, a pension almost always beats a LISA because the tax relief is more generous (40% vs 25%). The Lifetime ISA calculator projects the 25% bonus to a first home or age 60, and what the withdrawal charge takes back.
Don't overthink it
The most important thing is that you're saving and investing at all. The difference between a pension and an ISA matters, but it matters far less than the difference between investing regularly and not investing at all.
If you're paralysed by the choice, start with your employer pension match and put the rest in a Stocks and Shares ISA. You can always adjust later as your circumstances change.
Want to see how your ISA and pension fit into your overall net worth? Aureli lets you track everything in one place — free to get started.